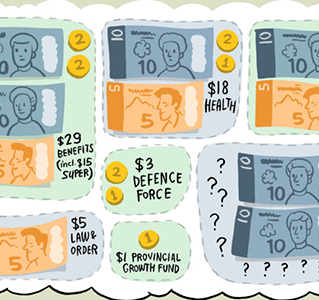
Last year this Government delivered its first fiscal plan – the Wellbeing Budget. Fire up the money cannon, because 2020 is going to be the year of the Recovery Budget.
Filter insights by:
Showing 16 of 179 content results
The COVID-19 tax measures should help businesses when they are hurting now. So why not allow businesses to carry their losses back instead of forward?
Natural disasters, pandemics and other black swan events cause significant stress or distress for many businesses. Each organisation will face a different set of circumstances – however cash management should be a the centre of everything a business does to navigate this unprecedented event, regardless of the challenges it’s experiencing.
International Valuation Standards (IVS) 2019 have been updated and include a new chapter, 'IVS 220 Non-Financial Liabilities' as part of the intangible asset standards. Non-financial liabilities require a non-cash performance obligation to provide goods or services, including deferred revenue obligations, warranties, environmental liabilities and loyalty program liabilities. IVS 2019 is available to IVSC subscribers here .
In October 2018, the IASB issued ‘Definition of a Business’ making amendments to IFRS 3 ‘Business Combinations’. The amendments are a response to feedback received from the post-implementation review of IFRS 3 (‘the Standard’). They clarify the definition of a business, with the aim of helping entities to determine whether a transaction should be accounted for as an asset acquisition or a business combination.
Despite dominating the political agenda for much of the year, tax was barely mentioned in the budget. That doesn’t mean the work there is over, writes Greg Thompson of Grant Thornton New Zealand.
Budget 2019: Unless we can find some way of taxing wealth as well as incomes, New Zealand is headed for an intergenerational economic meltdown, writes Grant Thornton tax partner Murray Brewer.
Now that we know what the Wellbeing Budget is, the question is how we can create the right political and social environment to support it, says Grant Thornton’s Barry Baker.
The requirements of Public Benefit Entities International Public Sector Accounting Standards (PBE IPSAS) for Not-for-Profit reporting entities are continuing to change. Navigating the Changes to PBE IPSAS for Not-for-Profits gives chief financial officers, and audit and risk committee members a high-level awareness of these recent changes to PBE IPSAS. It covers both brand new standards, and changes that have been made to existing ones.
To achieve a successful sale of a business and extract its maximum value, it’s critical that the planning process begins well in advance.
Gender diversity in business leadership is a no-lose proposition, yet progress is still slow. Grant Thornton International has been surveying thousands of businesses annually since 2004 about the levels of gender diversity in leadership roles globally.
The slow pace of change in gender diversity at a leadership level indicates there needs to be a shift in NZ’s business culture.
What might the 2018 Budget deliver on regional economic development, and how will it intersect with our largest city? In the first piece in a series analysing Budget 2018, Grant Thornton’s Murray Brewer casts his eye over the options and opportunities.
There are a growing number of mature medical practice owners who should be thinking about how they will exit their businesses. Bringing in the next generation to take over a legacy often presents challenges that threaten a successful transition.
There is no doubt International Accounting Standards have contributed significantly to the globalisation of the business world, crucially providing reliable and comparable information to investors for decision-making purposes.
The principles informing the valuation of professional practice interests have been relatively settled for some years. While this does not prevent differences in opinion regarding the value of a particular practice, it is helpful in ensuring the approach to valuation is (or should be) similar. This article explores some of the issues around their valuation.